At the counter · seconds
Shwetha, the cashier
Has this shopper paid?
A queue is waiting. She needs a quick confirmation, a list she can trust, and a way to put a wrong sale right.
Design for a glance, a sound and a short action.
Case study1 of 3
A clear view of a shop's money, from counter to bank.
I designed Amazon Pay's dashboard and phone app for merchants accepting scan-and-pay. Cashiers needed to confirm each shopper's payment; owners needed to reconcile it with the bank.
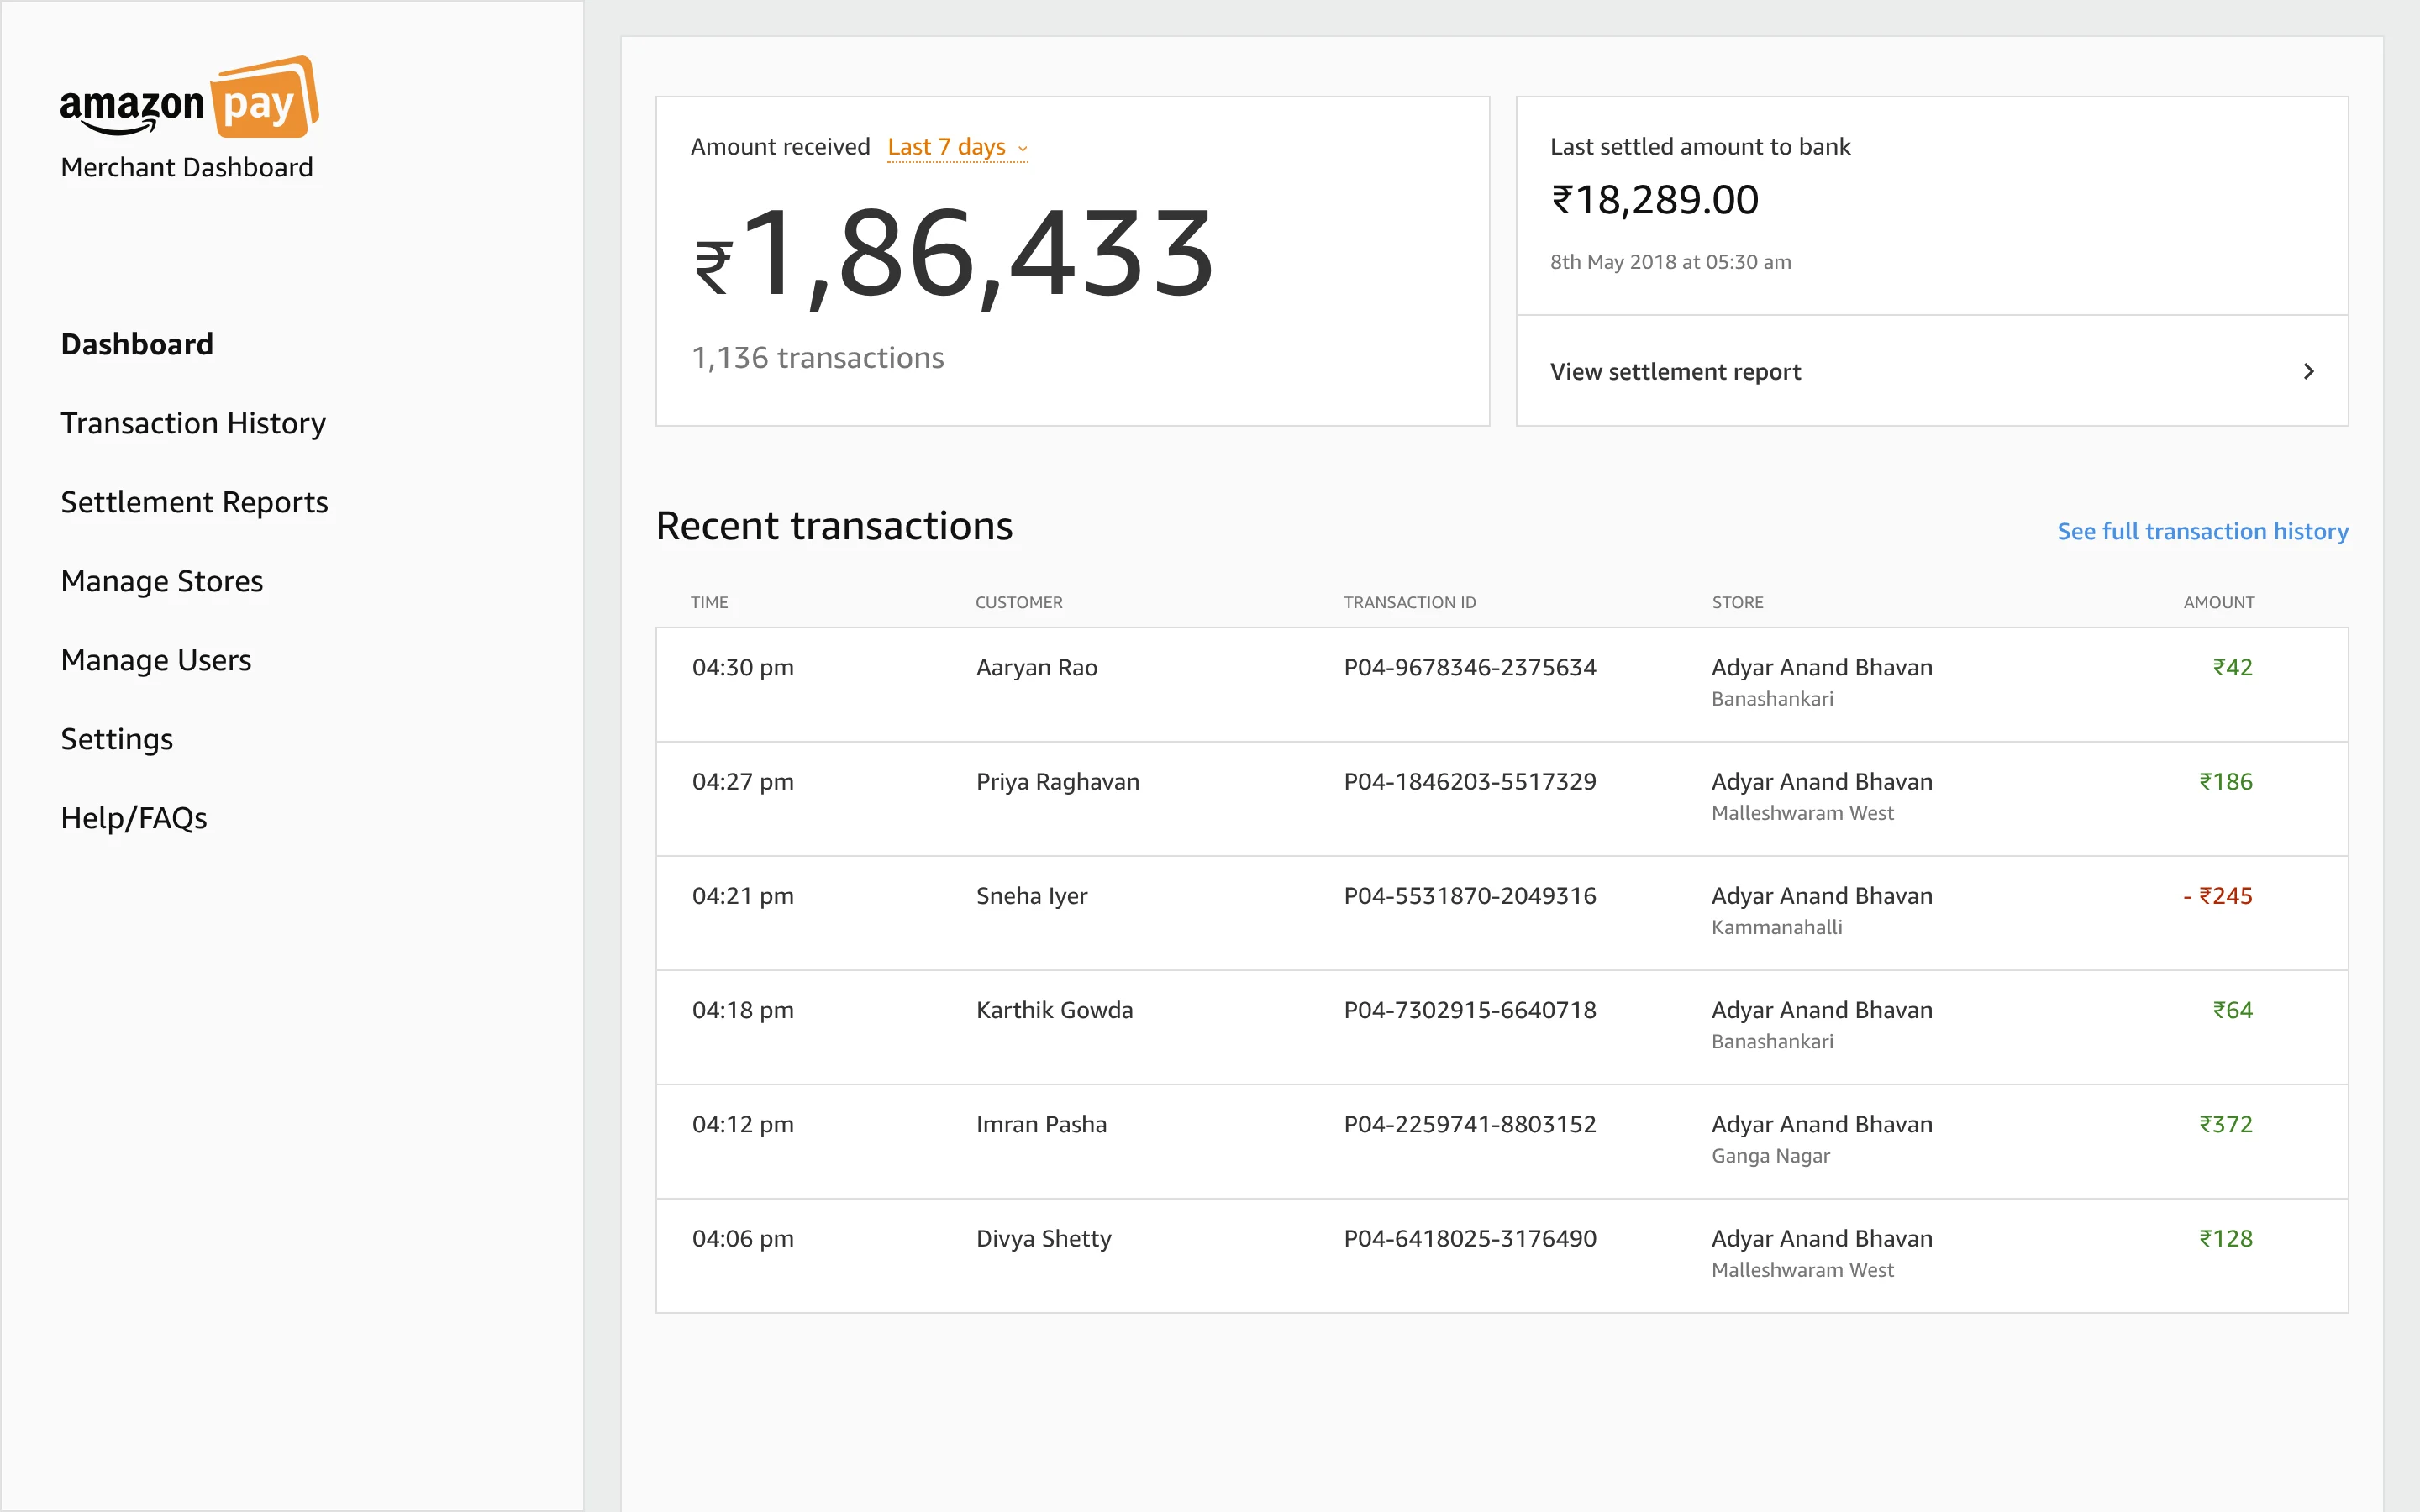
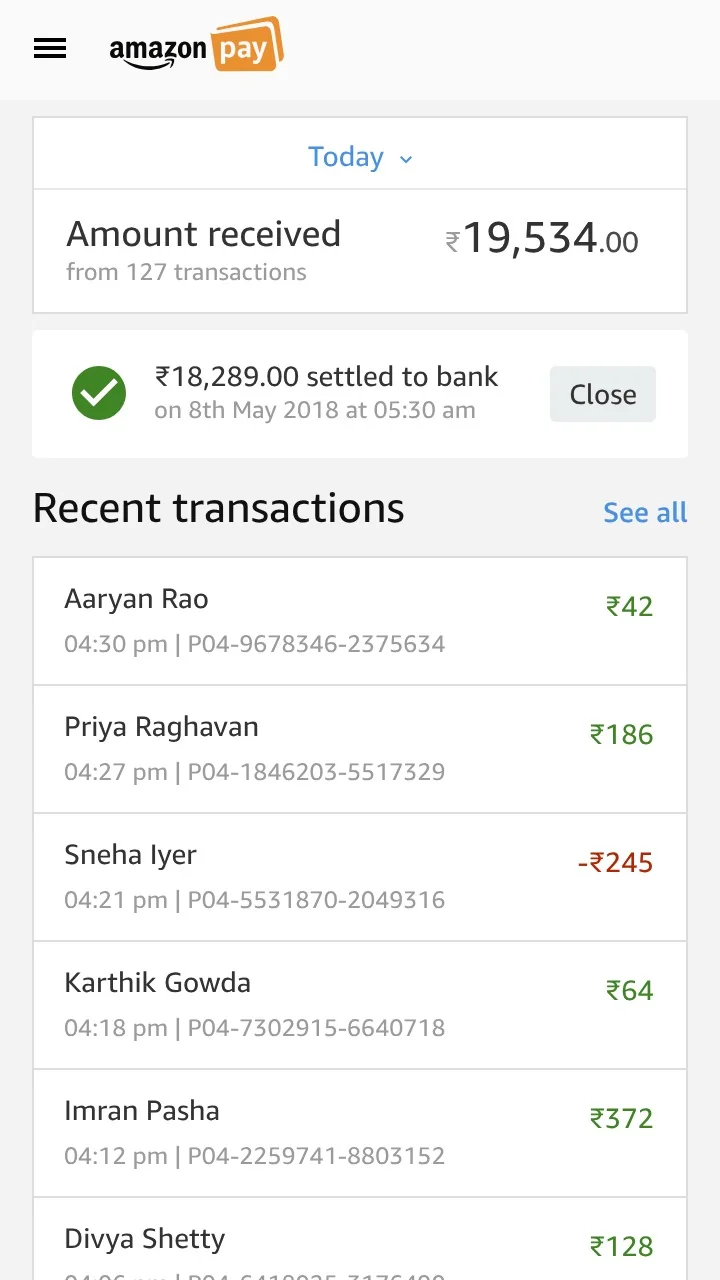
The merchant is Amazon Pay's customer here. The shopper is the merchant's customer. This product served the business receiving the money: its owner, managers and cashiers.
Amazon Pay was preparing to launch scan-and-pay. Merchants still pieced together payments from SMS threads and notebooks, then checked bank entries by hand. The consumer launch depended on giving them a working view.
As the sole designer on the merchant side, I spent two weeks visiting eleven merchants, then worked with PMs and engineers on the dashboard, refund rules and permissions. The desktop was the launch priority. The counters I visited made the case for a phone app next.
At a cafeteria, the cashier sometimes relied on the buzz of a confirmation message because the app loaded slowly. A tea-stall owner wanted one daily view across his four branches. Those visits shaped two distinct jobs.
At the counter · seconds
Has this shopper paid?
A queue is waiting. She needs a quick confirmation, a list she can trust, and a way to put a wrong sale right.
Design for a glance, a sound and a short action.
At the desk · close of day / next morning
What did we take, and did it reach the bank?
He oversees several stores and decides who sees what: managers see the stores assigned to them, cashiers get confirmations for theirs. He needs the day's totals together and a settlement record he can match to his bank statement.
Design for comparison, a date and a traceable record.
Composite personas based on the visits; names are stand-ins.
I used component libraries already cleared by InfoSec. The design work went into what happened when money arrived, moved or had to go back.
01 Confirmation · Shwetha, in seconds
A constantly reordering list could move a payment under the cashier's hand. A single arrival gets a highlight and a ding. A burst waits behind See N new transactions until she brings it in. The total updates either way.
It costs her one more tap in a rush, at a moment she chooses.
A plain ding survived overlapping payments. Spoken amounts through Alexa stayed out: there was no budget for hardware at every till.
02 Refunds · Shwetha, in seconds
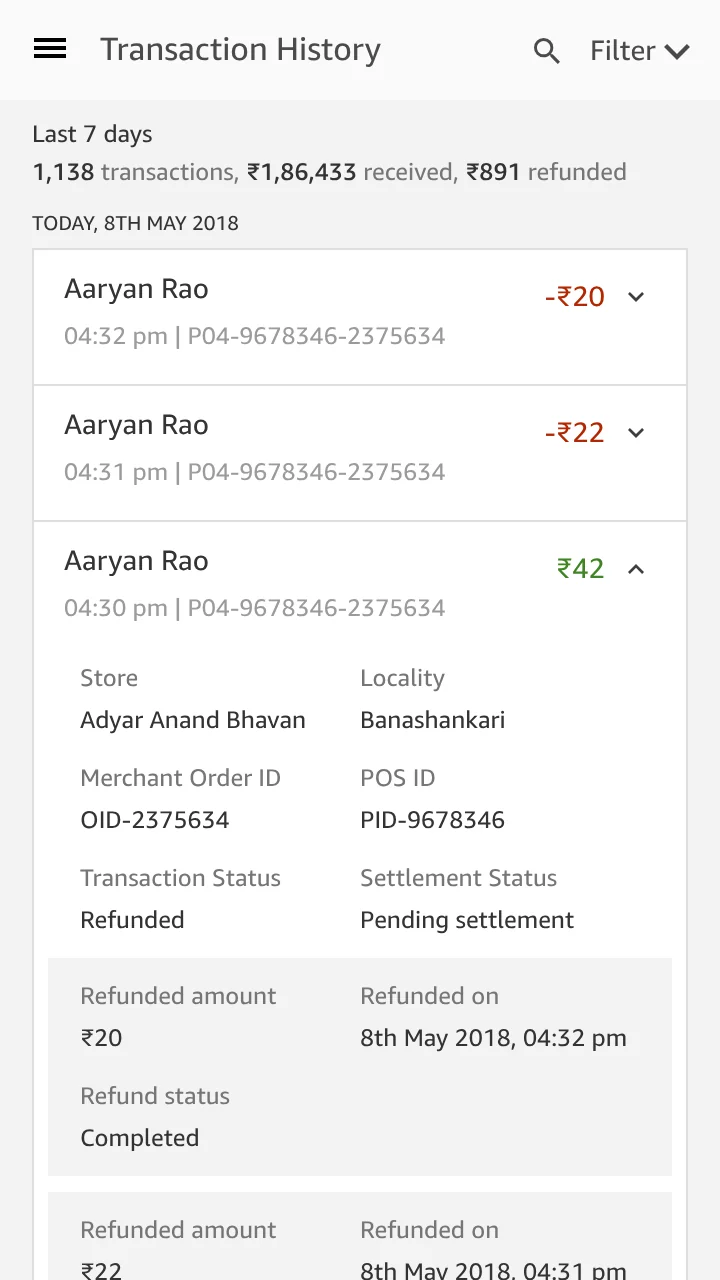
Refunds were often partial: ₹40 back when a shopper paid ₹100 for a ₹60 bill. The cashier can start from the original payment and issue several partial refunds, each recorded against that sale.
The safer-looking option was a manager's approval on every refund, which would have held the queue for someone rarely at the counter. With typical tickets under ₹500 and the planned fraud controls, the PMs and I kept approval out. The confirmation says Refund initiated; completion still depends on the bank.
That leaves no second pair of eyes on a refund, and large-value and fraud cases waiting for a later design.
What the phone carries
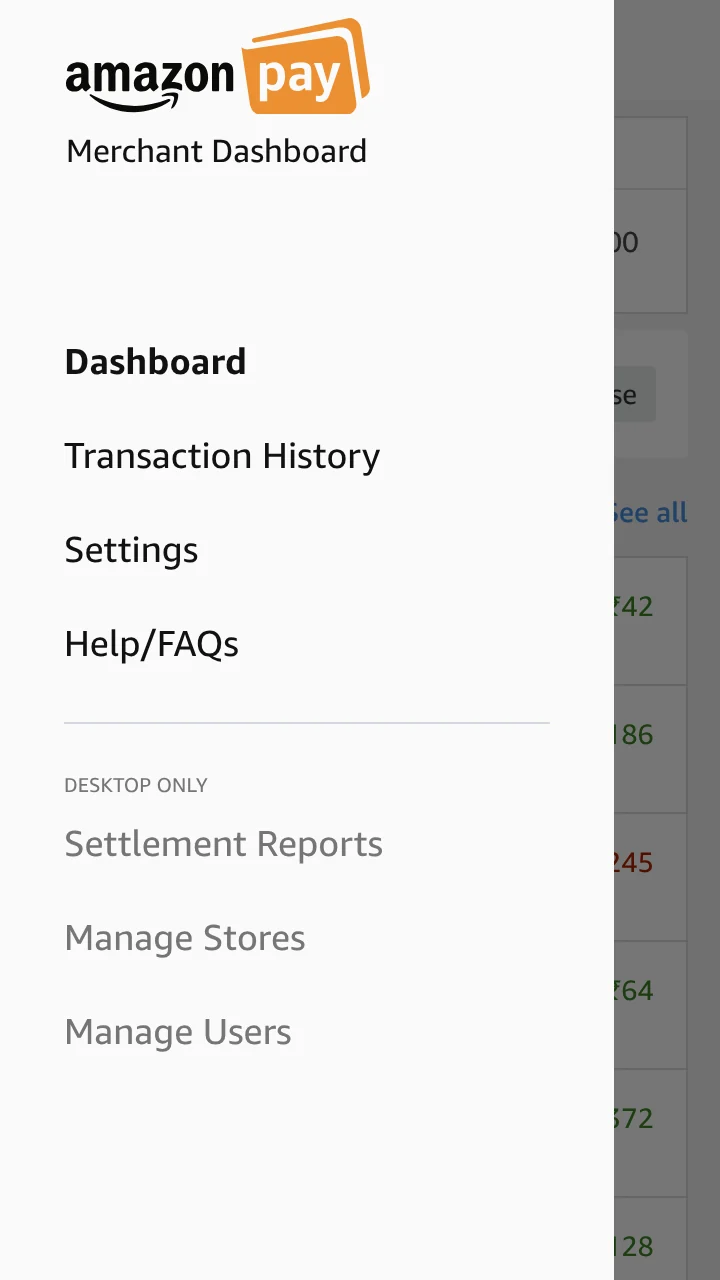
The visits also settled what the phone app would hold. Most counters had no laptop, so the phone carries the live feed, the ding and refunds; settlement reports, stores and users stay on the desktop, and the phone's menu marks them desktop only. Making the whole dashboard responsive would have put settlement tables on a screen nobody at a counter asked for.
An owner can't check a settlement from the shop floor.
03 Reconciliation · Prakash, the next morning
The printing-press merchant wanted to stop checking bank entries by hand. An amount received at the counter couldn't establish whether that money had arrived in the account.
A single balance would have been simpler to build, and it would have hidden exactly that gap. I separated received and settled amounts on the dashboard, with the settlement date visible, so the screen reports what the bank has done and never implies a payment is already in the account. The report groups a day's payments, deducts refunds, and shows the bank account and UTR reference for matching the deposit.
Prakash has a second number to learn on the first screen, and his morning question gets its answer there.
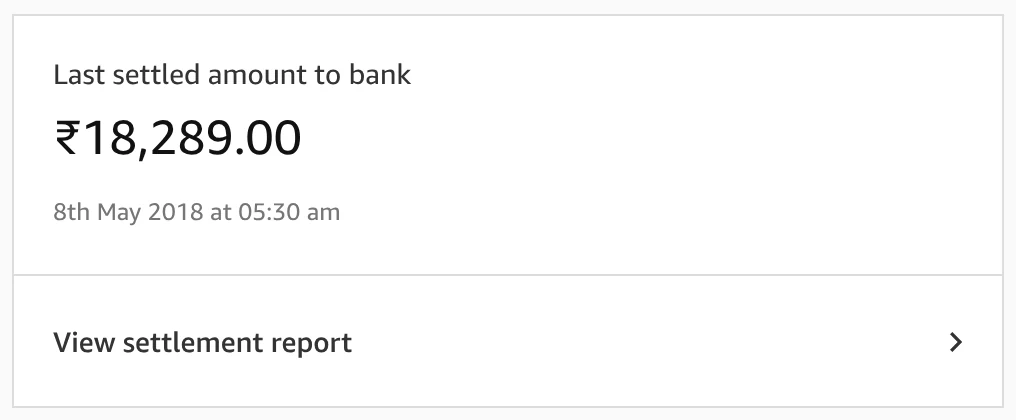
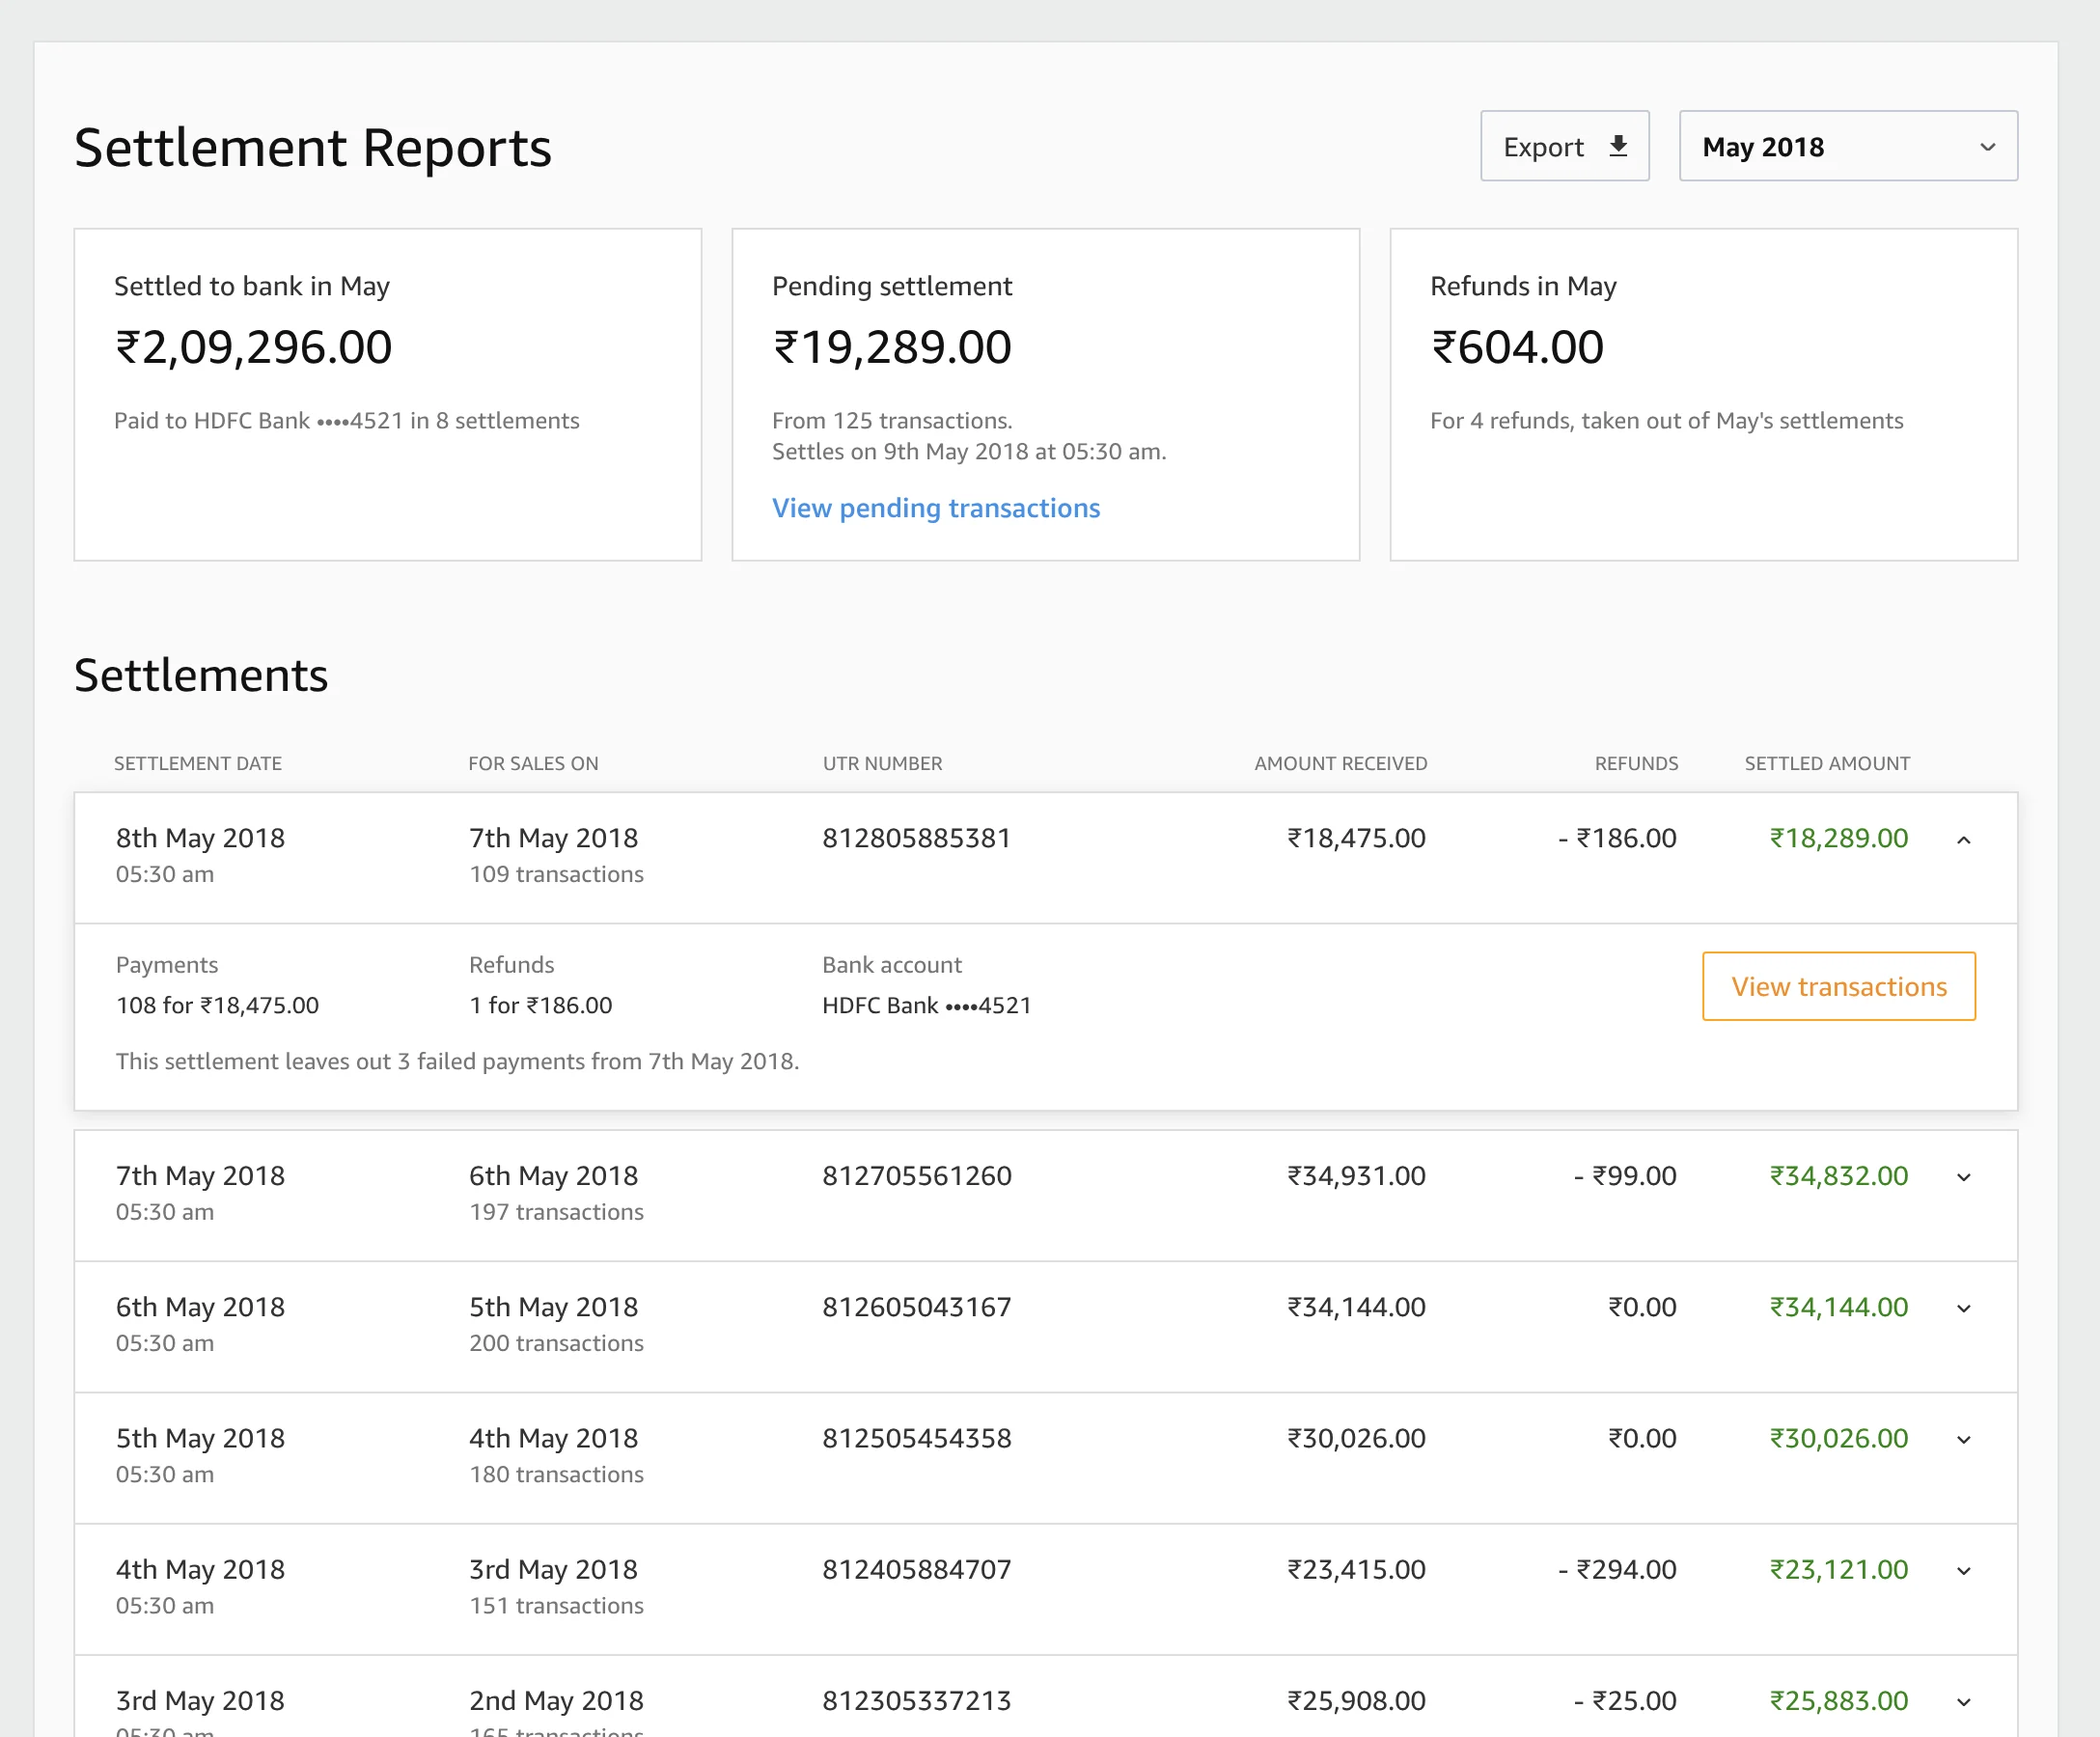
Merchants gained a live view of receipts, refunds at the counter and a record of settlement at the desk.
What I can claim
Both products reached production. I didn't receive post-launch usage figures, so I can't quantify adoption or time saved. Issue reports were the only feedback that came back to me.
What I'd carry forward
Bank-side refund failure and recovery states never got built. I'd design that interval between initiation and bank completion explicitly, and keep a written record of those trade-offs with stakeholders from the first week.
Watch a burst arrive, bring the new rows in, then open a payment to refund it.
Prototype Interactive, built from the real screens
Next case
Founding Designer